Explore this page
A client relationship is valuable.
A family relationship can carry it further.
You may know a client’s financial goals well while having fewer conversations with the spouse or adult children who may eventually make decisions about that wealth.
Estate planning gives Guided Financial a practical reason to bring those conversations forward: help the client act on an important need, then—with permission—connect the financial plan to the family members and decisions involved.
Value for the client
A defined route from “we need to address our estate plan” to an attorney-led engagement.
Value for Guided Financial
More opportunities to engage the household and support continuity of the advisory relationship when wealth transfers.
The relationship-building opportunity supports an AUM continuity strategy; it does not establish or guarantee retained assets.
You lead the financial relationship.
We coordinate estate plan fulfillment.
Identify the need, introduce the client, and coordinate the financial planning conversations.
Provide guided intake, workflow coordination, and visibility into authorized engagement milestones.
Handles all things requiring legal advisement to eliminate any/all risk to the advisor.
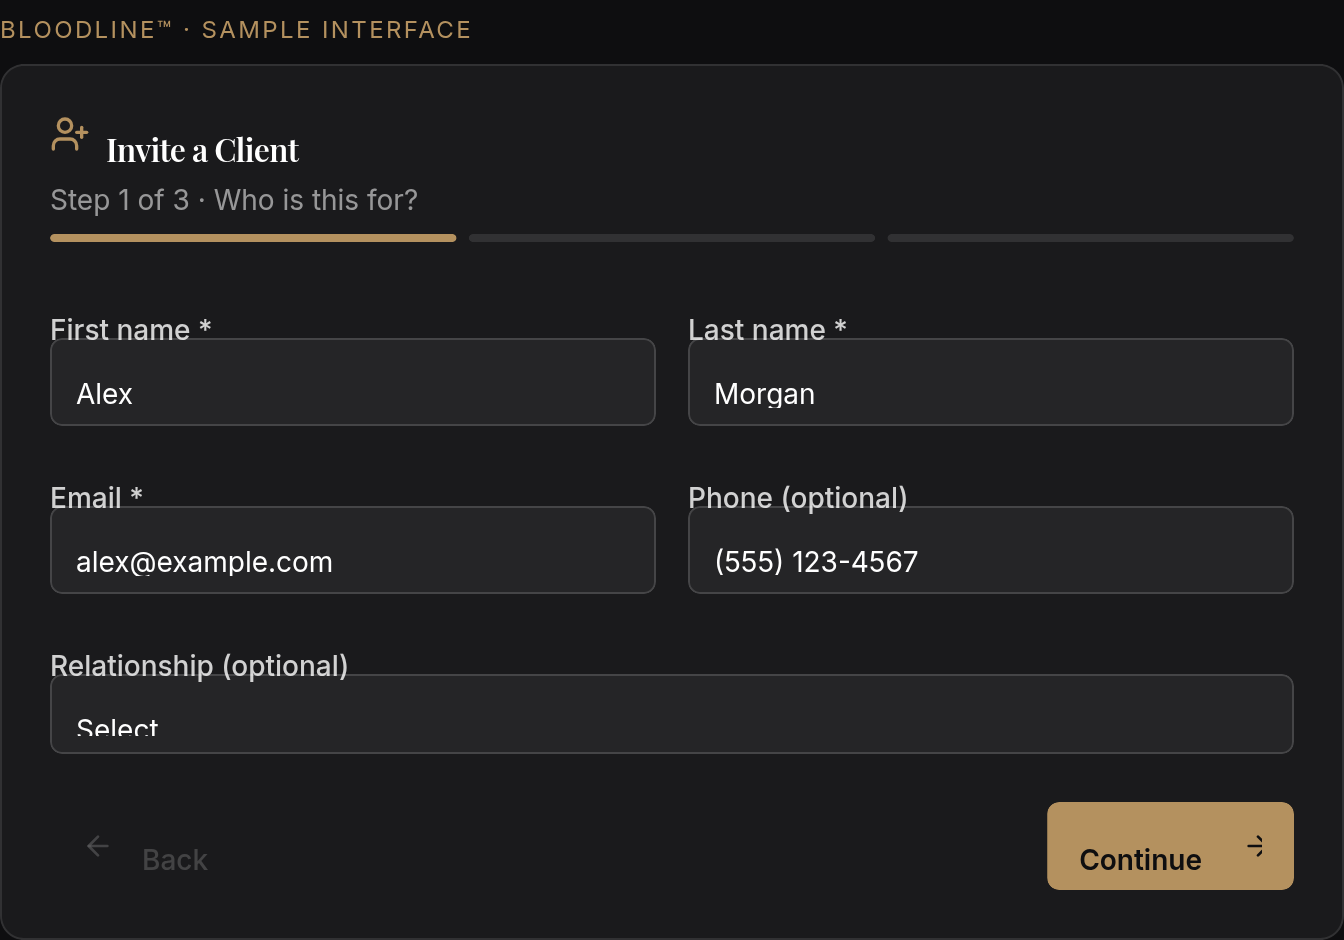
Start with two households.
Evaluate the work together.
Let us handle the first 2 plans at no cost. This will allow both our teams to establish the most efficient, non-disruptive fulfillment workflow.
- Access Advisor DashboardOnboarding.
- Introduce two suitable households.Invite first 2 clients
- Fulfill and deliverClients complete intake. Bloodline coordinates the workflow, fulfills and delivers.
- Review the experience before expanding.Discuss client feedback, refine collaborative workflow as needed.
Expanding without creating entropy
To be discussed.
Proposed pilot sequence and evaluation criteria. Final scope, timing, and responsibilities remain subject to agreement.
Measurables we can track
Agree on a small set of measures before inviting clients. These are proposed review criteria—not claims about results already achieved.
Which agreed milestones were completed, and where did clients need help?
How much time did the team spend introducing and coordinating each household?
Did clients understand the process, responsibilities, and next steps?
Were useful spouse, heir, or financial follow-up conversations identified with client consent?
A two-household pilot can test delivery and fit. It cannot establish a long-term AUM retention rate.
Recap + a clear starting point.
- Pilot offer
- Two qualifying client matters with estate plan fees waived, subject to agreed scope.
- Rollout
- Choose a commercial arrangement after reviewing the pilot and confirming the firm’s requirements.
- Launch support
- Client communications, co-branded materials, and a possible joint webinar can be scoped separately.
What if a household needs more complex planning?
Confirm suitability before starting. Work beyond the standard engagement requires separately agreed legal scope; the pilot should not imply that every household qualifies.
What will Guided Financial be able to see?
Authorized engagement progress and permitted information. Client consent and confidentiality obligations determine access.
Does creating an account begin the pilot?
No. The current offering states that registration is free and does not begin the pilot or commit Guided Financial to a paid rollout.
06 / PARTNER REGISTRATION
Create your partner account.
Create your login or sign in first, then complete your firm profile.
Free to join · No commitments