Find Out How Much Of Your Retirement Income Rides On The Market (Then Get One Written Plan To Protect It)
Score Your Retirement Income PlanFree. 2 minutes.Move The Sliders. See What's At Risk.
That's how much of your savings would be riding on one bad stretch.
Illustrative math only. Nothing is stored.When You Were Working, A Bad Year Was Just A Bad Year.
You kept contributing. You waited. It came back.
Retirement changes the math.
Now you're withdrawing while it's down.
And shares you sell at the bottom don't come back.
Same market. Different stage of life.
Completely different risk.
Your Savings Have Three Jobs Now:
Income
Pays the bills every month. Planned to be steady, not hopeful.
Growth
Keeps up with rising costs over a retirement that can last 30 years.
Legacy
Reaches the people you choose, without a mess.
One Written Plan. Four Parts.
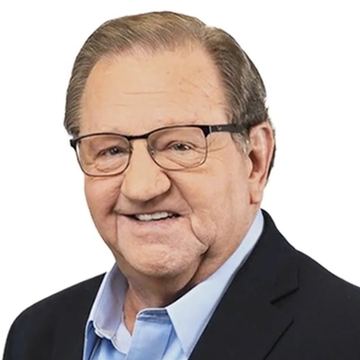
Meet Len Strickler
Managing Partner and co-founder of LSF Capital, a retirement-focused firm in Fort Lauderdale. He works with retirees and pre-retirees on retirement income and principal protection strategies, including fixed indexed annuities and other insurance products.
He co-hosts the educational radio and TV program Let’s Talk Safe Money®, and wrote Way of the Financial Warrior.
But none of that matters unless your income plan holds up in a bad year.
Income Is Half The Plan. Who Inherits It Is The Other Half.
Answer plain-English questions online. A licensed attorney reviews every plan. Then Len checks it against your accounts and beneficiaries.
Typical documents shown. What you need depends on your situation.
Would Your Plan Survive A Bad Decade? Score It In 2 Minutes:
0 / 8
Tap an answer for each one.
Fair Questions:
"Is this about annuities?"
Sometimes they fit. Sometimes they don’t. The plan comes first. A product only if it serves the plan.
"I'm already retired. Is it too late?"
No. Retirees and people close to retirement are most of who LSF Capital works with.
"Will I get pressured?"
Start with the check. You see where you stand before anyone recommends anything.
"Who writes my legal documents?"
Not LSF Capital. A licensed attorney at The Succession Firm, a separate law firm, reviews your plan under its own engagement with you.
"What does it cost?"
That depends on your situation. If a recommendation involves an insurance product, you see how it is paid before you decide.
The Next Downturn, With A Plan
Your bills are covered by money that isn’t riding on the market. You watch the news. You don’t panic.
The Next Downturn, Without One
You watch the balance fall. You sell to pay the bills. And you hope it comes back in time.
Two minutes. Four questions.
Your call.